Part 2 — CORPORATION ACCOUNTS (continued 2)
Reading edition
Charge material 315.00
—13—
Drew check No. 5. for 2 weeks' pay-roll 220.50
Charge machinery for cost of installing 178.50
Building maintenance for repairs to building per pay-roll distribution 42.00
—15—
Gave Derby Desk Co.
Check No. 6
To pay bill of March 1 350.00
—15—
Gave Slade Oil Co.
Check No. 7
To pay bill of March 5 54.25
Less 3% 1.63 52.62
———
—17—
Gave Francis & Co.
Check No. 8
To pay bill of March 7 640.00
Less 3% 19.20 620.80
———
—18—
Gave Stevens & Co.
Check No. 9
To pay bill of March 8 225.00
Less 3% 6.75 218.25
———
—19—
Eureka Tool Co.
Invoice No. 12, terms N/30
Charge tools 250.00
—20—
Check No. 10 for 1 week's pay-roll
Charge labor 326.25
Charge tools 27.50 353.75
———
(Making tools for shop per pay-roll distribution)
—22—
Received from Danforth & Co.
Credit memo for damaged goods in lot covered by invoice dated 3/12 63.00
Credit material
Gave them check No. 11
For acct. 252.00
Less 2% 5.04 246.96
———
—27—
Check No. 12 for 1 week's pay-roll 342.70
Charge labor per pay-roll distribution
—30—
Gave Norwich Machine Co.
Note of Henry Farwell 5,000.00
Accrued interest 25.00 5,025.00
———
Gave them check No. 13 to pay their account 3,475.00
—31—
Salaries check No. 14 for salaries of Supt. & Clerks 350.00
63. Manufacturing Data. The following data has been collected by the bookkeeper from the reports of superintendent and foremen, and from the inventories taken at the end of the month.
Material issued to factory 1,003.35
Material used for building repairs 50.00
Inventories
Supplies 45.00
Rent (unexpired) 300.00
Power, heat, and light (Coal) 150.00
Office supplies 140.40
Goods in process—material 602.00
Labor 400.00 1,002.00
———
We will now close the ledger to ascertain manufacturing results for the month, by making the following adjusting entries in the journal—
Debit Manufacturing Account
for material issued to factory.
Debit Building Maintenance and Repairs
for material used in repairs.
Credit Material Purchases
for both of the above.
Debit Manufacturing Account
for Labor Account
for Supplies used—found by deducting inventory from supplies purchases.
for Salaries Account for Rent one month for Power, Heat, and Light—found as above for Building Repairs for Office Supplies—found as above Credit accounts representing above for amounts charged.
The manufacturing account will now show, on the debit side the total manufacturing expense for the month. The next step is to find the cost of finished goods to be credited to manufacturing account and charged to finished goods account. Our inventory of goods in process, which includes material and labor only, amounts to $1,002.00. The labor account and reports from foremen show that the amount of these items used in the factory is $1,672.30. In round numbers, the former is 60% of the latter, that is, sixty per cent of the work started is still in process. We will assume, therefore, that this is a fair percentage to be used in determining the expense items invested in goods in process. Taking 60% of the total manufacturing expense gives $1,400.13, which, deducted from the total, leaves $933.42 as the cost of finished goods.
In this case the per cent of goods in process is large for the reason that it is the first month of operation. The results in succeeding months will be more nearly equal. If the factory is running regularly, turning out practically the same quantities each month, the quantity of finished goods will just about equal the work started in any one month.
Should we wish to show a factory profit of 10%, it will be necessary to add 10% to the cost of finished goods which will then represent the cost to be used by the sales end of the business. Since we have no account to which this amount can properly be credited, we will open a new account called contingent profits, which will be closed into profit and loss at the end of the year.
Since we are not closing the books for the purpose of making a balance sheet, we do not close the expense accounts into an expense inventory account as explained in article 59. Instead, the balances are allowed to stand until such time as the books are finally closed.
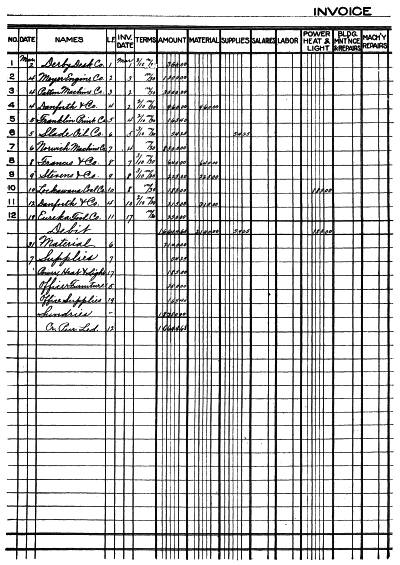
Invoice Register with Distribution Columns.
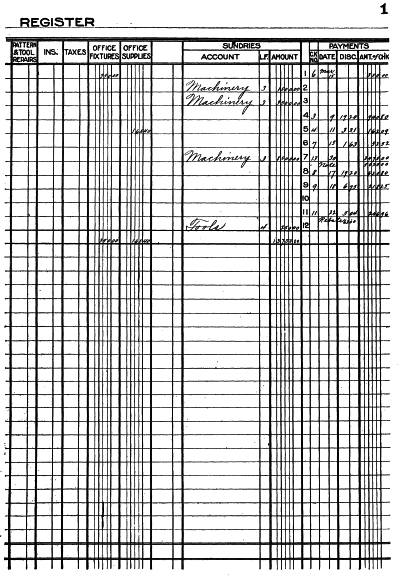
Invoice Register with Distribution Columns
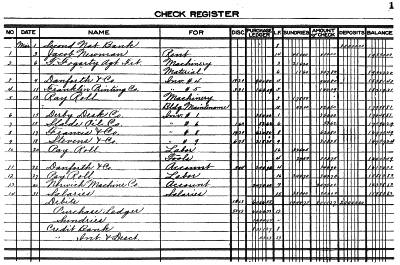
Check and Disbursement Record
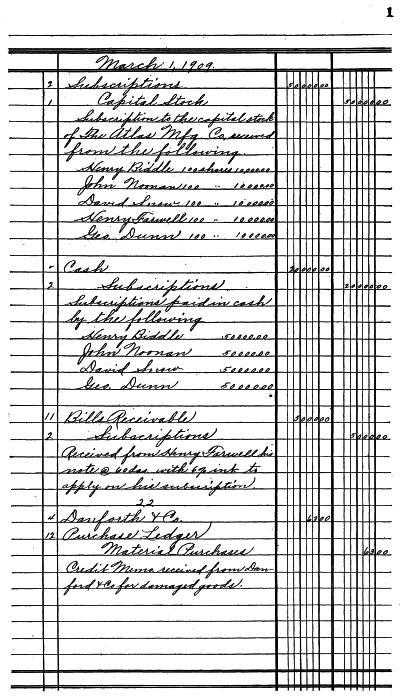
Manufacturing Journal
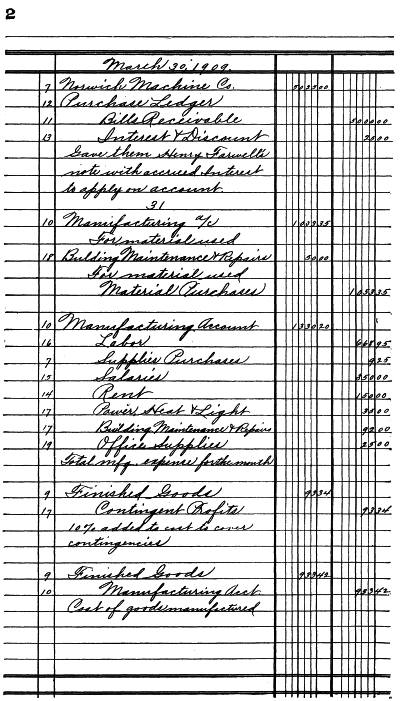
Manufacturing Journal
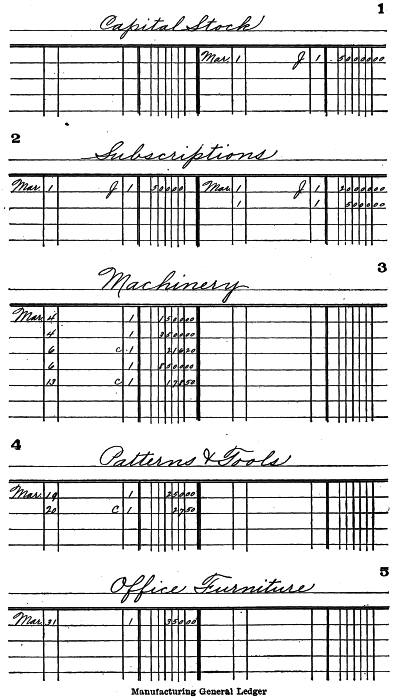
Manufacturing General Ledger
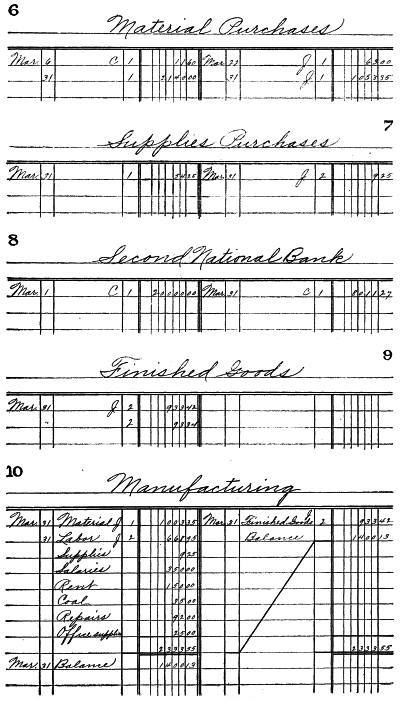
Manufacturing General Ledger
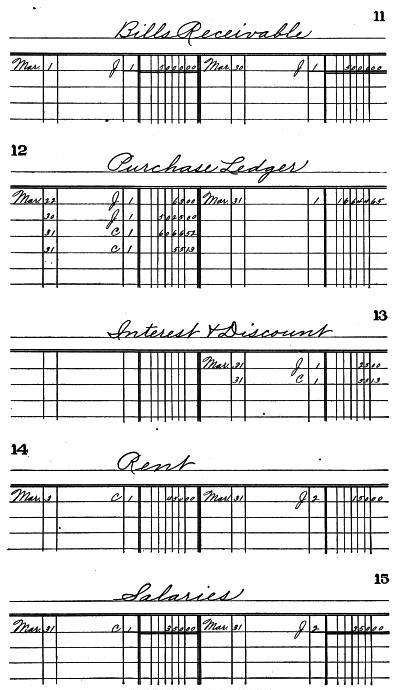
Manufacturing General Ledger
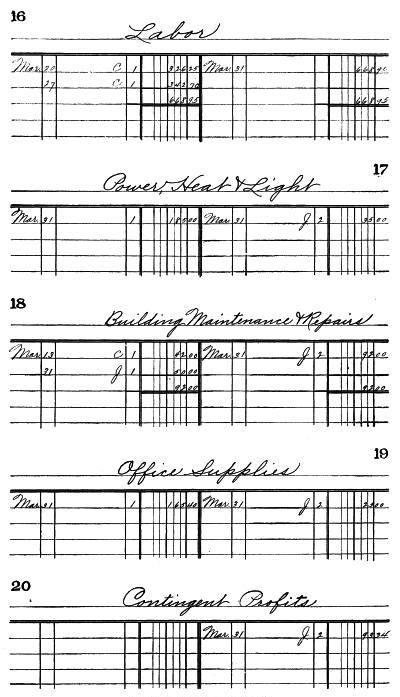
Manufacturing General Ledger
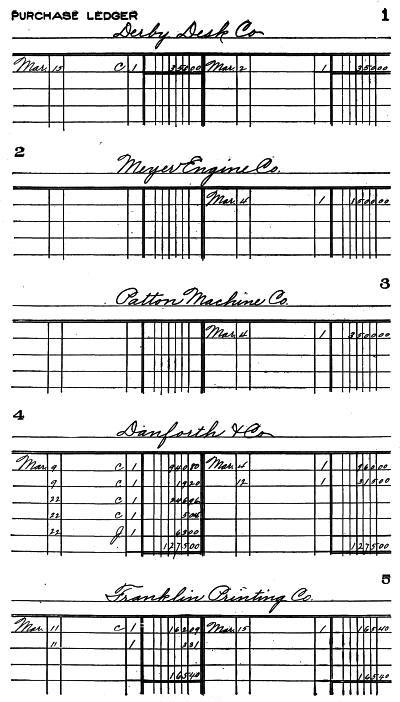
Purchase Ledger
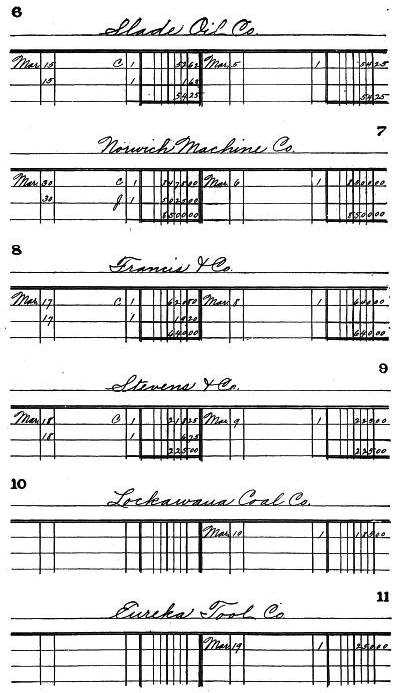
Purchase Ledger
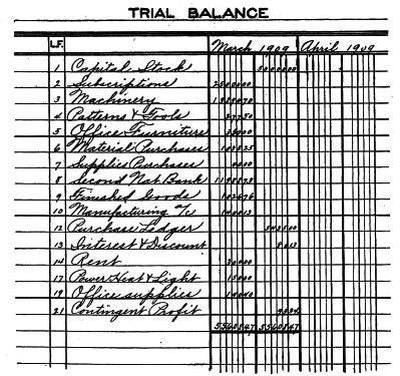
General Ledger Trial Balance
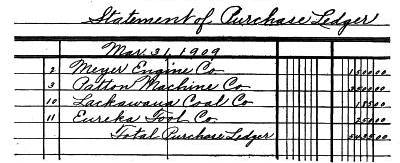
Purchase Ledger Statement
EXERCISE
The transactions given in this exercise are a continuation of the business referred in to the preceding articles. During the month of April the following transactions are recorded.
Material purchases $2,670.00
Supplies purchases 127.50
Patterns and tools purchases 150.00
Cash received on subscriptions 25,000.00
Deposited in Bank 25,000.00
Checks drawn
Purchase accounts 5,500.00
Salaries 375.00
Pay-rolls 1,670.20
distributed as follows:
Labor $1,652.70
Machinery repairs 17.50
David Snow 10,000.00
(Stock purchased at par by Company)
The following data is obtained from the reports of foremen and inventories taken at the end of the month:
Material issued to factory to be used in manufacturing goods. 2,261.00
Material used in machinery repairs 16.70
Inventories, April 30
Supplies 147.00
Rent (unexpired) 150.00
Power, heat, and light (Coal) 75.00
Office supplies 118.40
Goods in process—material 615.00
Labor 410.00 1,025.00
———
1. Find value of goods in process, using the same percentages in estimating expense items as shown for material and labor.
2. Make journal entries closing accounts into manufacturing account to show cost of goods completed during the month.
Note:—To find total cost of material and labor, used and partly used, add to the amounts shown for one month the inventory of the same items at end of preceding month.
3. Make trial balance of general ledger after books are closed as shown in model set.
GENERAL OFFICES OF THE A. B. DICK COMPANY, CHICAGO, ILL.